
One Big Beautiful Bill Act: Significant Tax Changes
Significant Tax Changes from the One Big Beautiful Bill Act (OBBBA)
Individual Taxation in the OBBBA
1. 2017 Tax Cuts Made Permanent
Makes the 2017 Tax Cuts and Jobs Act (TCJA) tax brackets and standard deduction permanent for all taxpayers, preventing any scheduled tax increases for tax year 2026. Higher rates are now permanently removed.
2025 Tax Bracket Comparison: "Old" vs. OBBBA (Made Permanent)
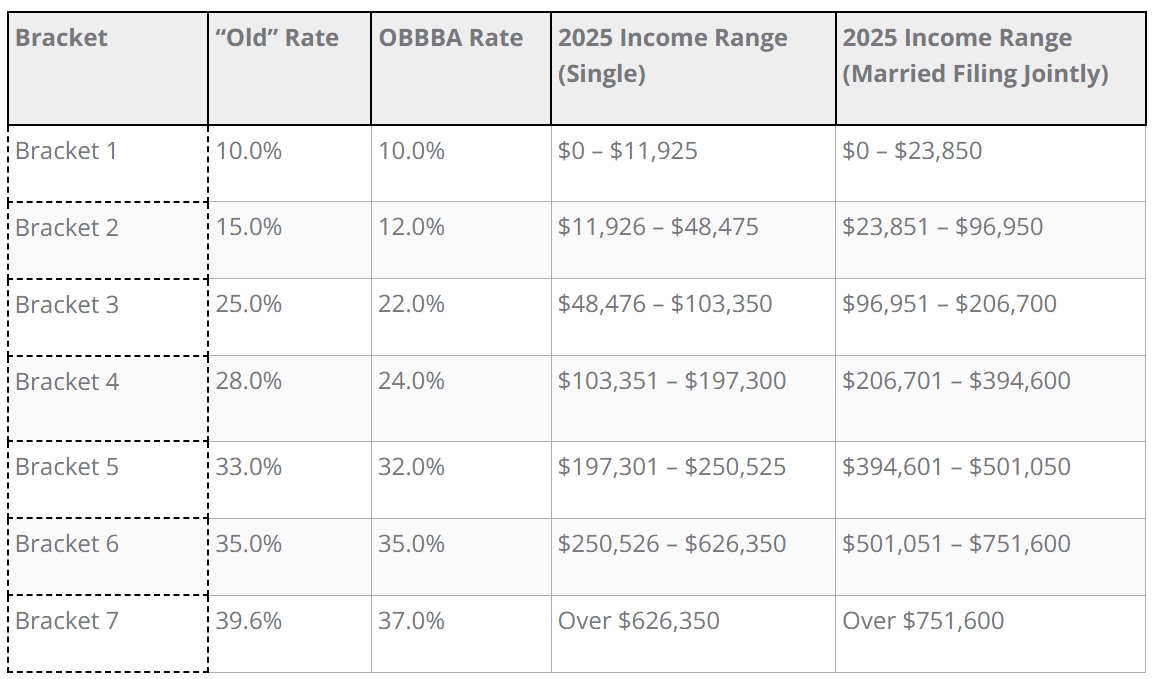
Note: These are 2025 inflation-adjusted federal tax brackets. Under OBBBA, the Tax Cuts and Jobs Act's (TCJA) lower rates and structure are made permanent and will continue to adjust annually for inflation.
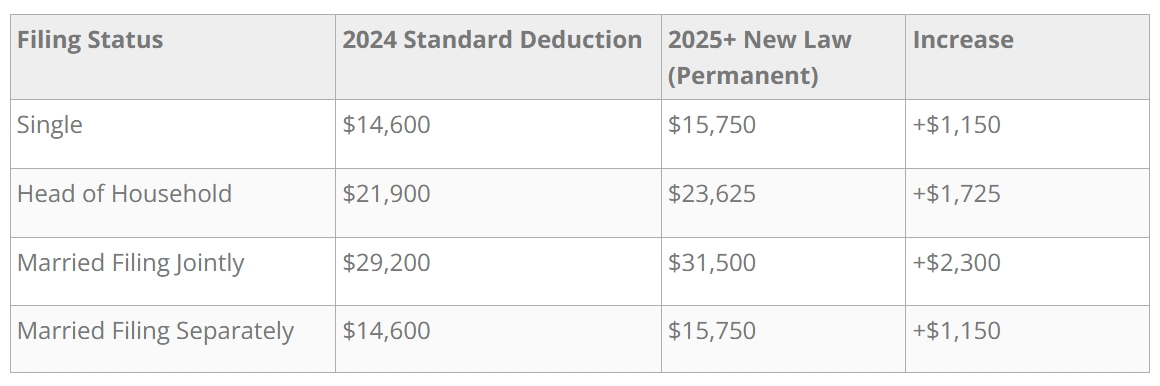
Higher Standard Deduction Made Permanent - Comparison: 2024 vs. 2025 and Following
Standard Deduction by Filing Status
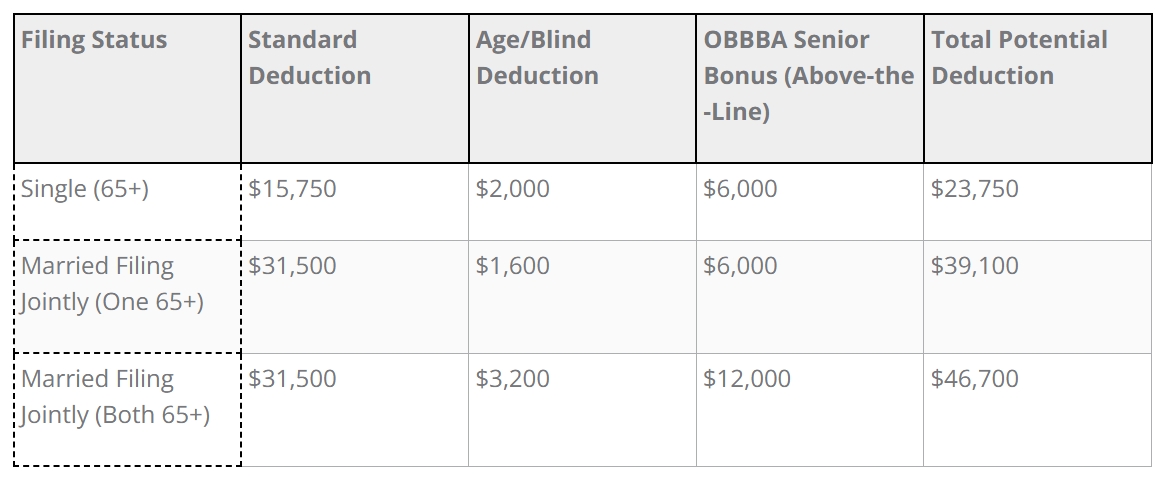
2025 Senior Tax Deduction Summary - Effective for Tax Year 2025
This table summarizes the total federal tax deduction available to senior taxpayers (age 65 and older) under OBBBA for the tax year 2025. The new $6,000 senior above-the-line deduction (up to $12,000 per couple) is in addition to the standard deduction and the traditional age-based extra deduction.
All 2025+ standard deductions are indexed for inflation.
2. $2,200 Child Tax Credit - Effective for Tax Year 2025
Raises the child tax credit to $2,200 per child. The refundable portion of the credit, referred to as the Additional Child Tax Credit (ACTC), is adjusted for inflation and, for the 2025 tax year, is set at $1,700. The credit begins to phase out for taxpayers with adjusted gross income (AGI) in excess of $400,000 in the case of married taxpayers filing jointly and $200,000 for all other taxpayers. It completely phases out when the taxpayer’s modified adjusted gross income (MAGI) reaches $ 240,000 and $440,000 for MFJ.
3. Tip Income Deduction
Creates an above-the-line deduction of tip-based earnings capped at $25,000 per individual. The deduction is phased out by $100 for each $1,000 by which the taxpayer’s MAGI exceeds $150,000 ($300,000 MFJ) and completely phases out when the taxpayer’s MAGI reaches $400,000 ($550,000 MFJ). Effective for 2025 through 2028.
4. Overtime Pay Deduction
Creates an above-the-line deduction for qualified overtime compensation. Maximum annual deduction is $12,500 ($25,000 for joint filers). The deduction is phased out by $100 for each $1,000 by which the taxpayer’s MAGI exceeds $150,000 ($300,000 MFJ) and completely phases out when the taxpayer’s MAGI reaches $275,000 ($550,000 MFJ). Effective for 2025 through 2028.
5. New Car Loan Interest Deduction
Permits up to $10,000 of interest deduction on a qualified passenger vehicle. Must be new auto loans for U.S.-assembled cars bought 2025–2028; begins to phase out for singles over $100,000 or joint filers over $200,000, and completely disappears where income exceeds $150,000 for singles and $250,000 MFJ. Above-the-line deduction. Car must be for personal use - not a business asset.
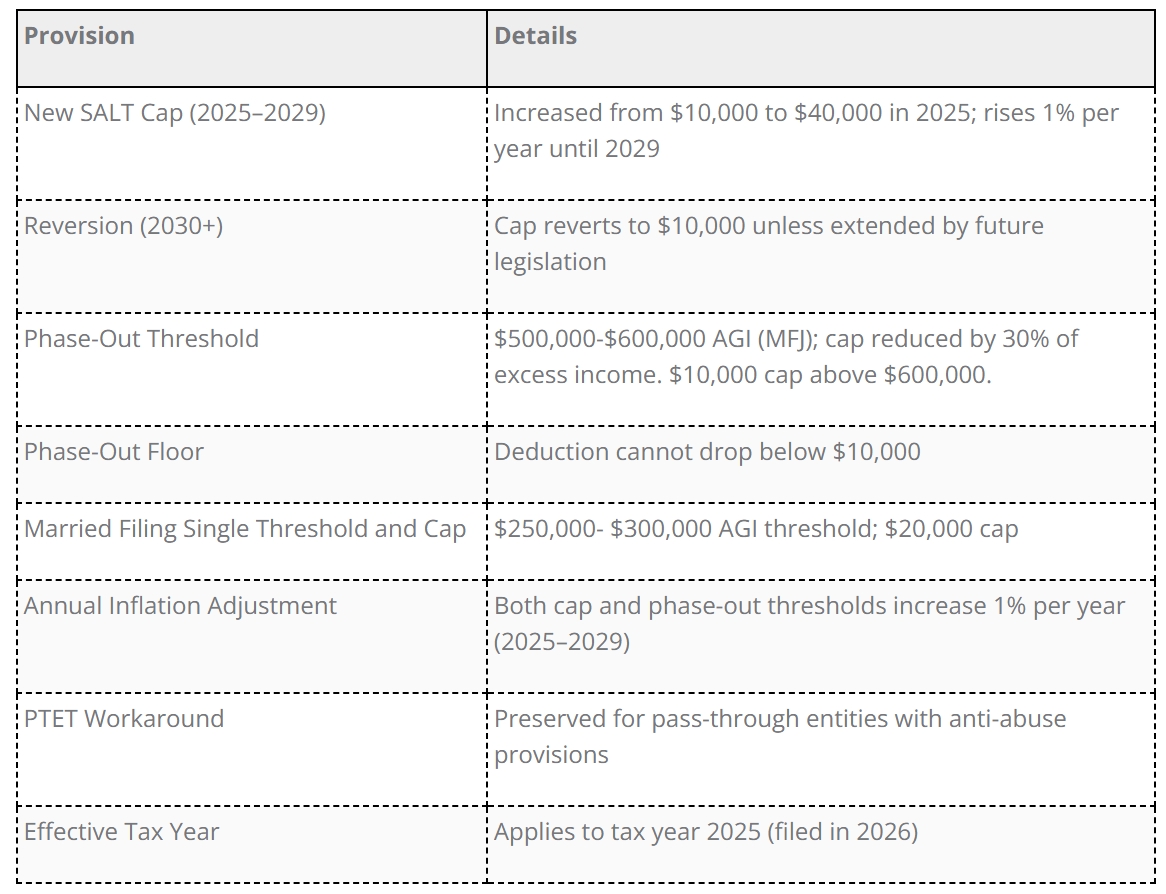
6. Temporary State and Local Tax (SALT) Cap Increase
Raises SALT deduction to $40,000 ($20,000 MFS) for households earning below $500,000 in 2025, phasing out between $500,000 and $600,000, but not below $10,000. Reverting to $10,000 in 2030.
7. Special Senior Bonus Deduction - Effective for 2025
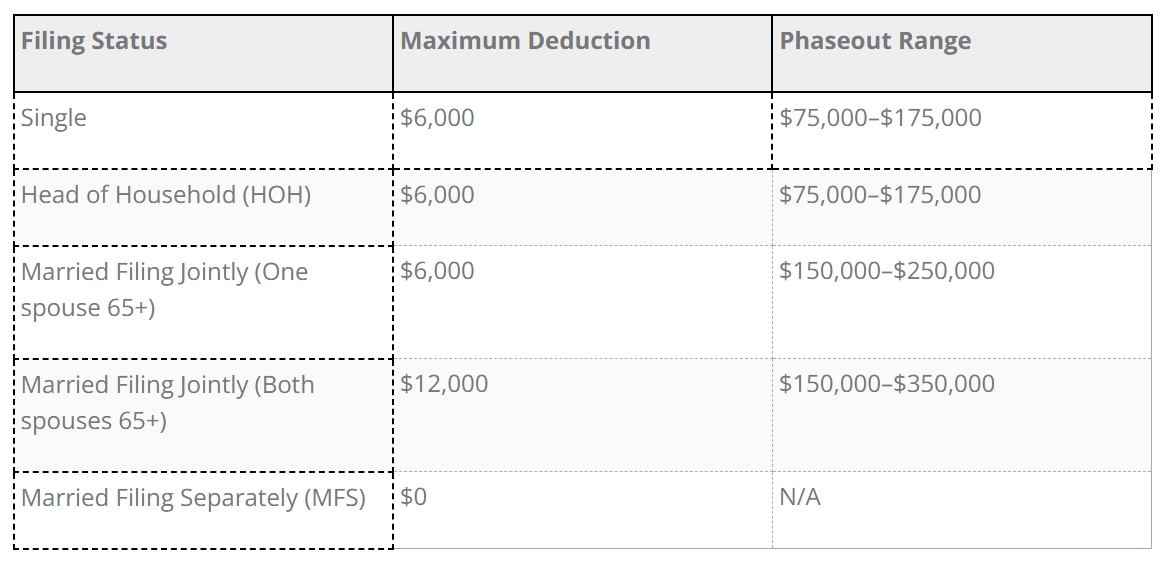
Effective for 2025 through 2028, individuals who are age 65 and older may claim an additional above-the-line deduction of $6,000 ($12,000 total for a married couple where both spouses qualify). This new deduction is in addition to the current traditional age-based extra deduction standard deduction for seniors under existing law. This special deduction is “in lieu” of the “No Tax on Social Security” campaign promise. The deduction is available for both itemizing and non-itemizing taxpayers. The $6,000 exemption deduction begins to phase out by 6% by which a taxpayer’s MAGI exceeds $75,000 ($150,000 MFJ) and varies by filing status as detailed below:
8. "MAGA" Newborn Savings Accounts / Trump's Accounts - Effective for 2026
Taxpayers can make an election on behalf of their eligible child to have $1,000 treated as a tax payment for the taxable year. The $1,000 will be deposited into a Trump account established on behalf of the child. An eligible child is defined as a U.S. citizen child born in 2025 through 2028 for whom no previous election has been made. The account is treated in the same manner as an IRA (cannot be a ROTH IRA) with special rules during the period when the beneficiary is under age 18.
Additional contributions to the Trump accounts can be made from parents, relatives, and other taxable entities, as well as nonprofit and government entities. Contributions to the accounts can only be made after-tax (except for employer contributions up to $2,500, which can be pre-tax) if made prior to the child turning age 18, and aggregate contributions are limited to $5,000 annually (adjusted for inflation beginning with the 2028 taxable year).
The funds from the accounts cannot be distributed prior to the calendar year in which the child turns age 18. Distributions will be taxed like any other IRA. Because the contributions made by parents and other relatives are made after-tax, these contributions would not be subject to tax when withdrawn.
No income cap specified.
9. Charitable Donations - Effective for 2026
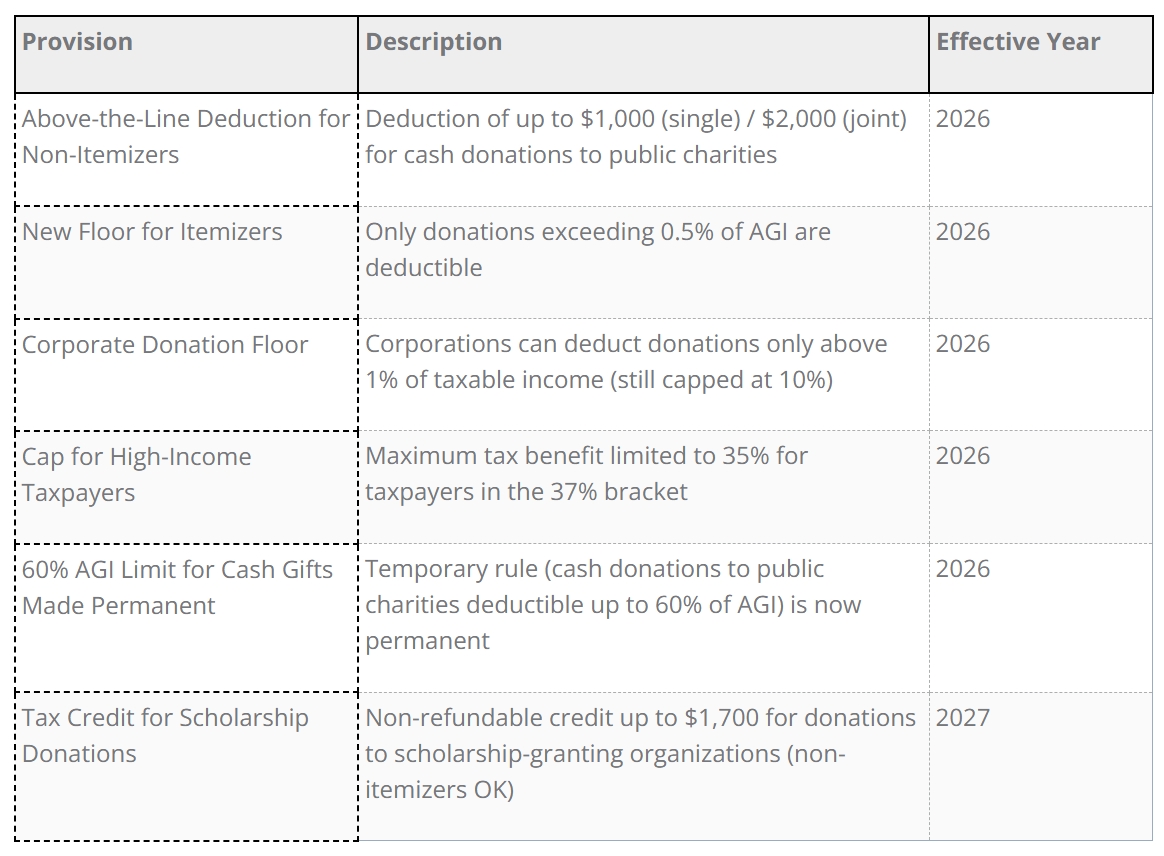
Establishes a new above-the-line charitable contribution deduction of up to $1,000 for single filers and $2,000 for married couples filing jointly, available to non-itemizers making cash donations to qualified charitable organizations. No income limitation applies to this deduction, thereby broadening access and encouraging wider participation in charitable giving.
The existing rule allowing deductions for cash gifts to public charities up to 60% of AGI is made permanent.
For itemizing taxpayers, beginning in tax year 2026, the charitable deduction will only be allowed if total contributions exceed 0.5% of the taxpayer’s AGI. This introduces a new minimum threshold for deductibility of itemized charitable contributions.
Summary of OBBBA Charitable Donation Provisions
10. Estate and Gift Tax Exclusion Raised to $15M Per Taxpayer - Effective for 2026
Removes the potential 50% reduction permanently – makes the higher exemption permanent. The $15 million per individual ($30 million for married couples) exclusion will be inflation-adjusted annually and also applies to the generation-skipping transfer tax exemption.
11. Capital Gains Tax Step-Up Preserved
Maintains the step-up in basis for inherited assets, avoiding capital gains tax at death.
12. Repeal Clean Energy Credits – Effective for Tax Year 2025
Eliminates green-energy credits (EVs, solar, wind, hydrogen, etc.), with some as early as September 30, 2025.
Federal Energy Efficiency Tax Credits Overview
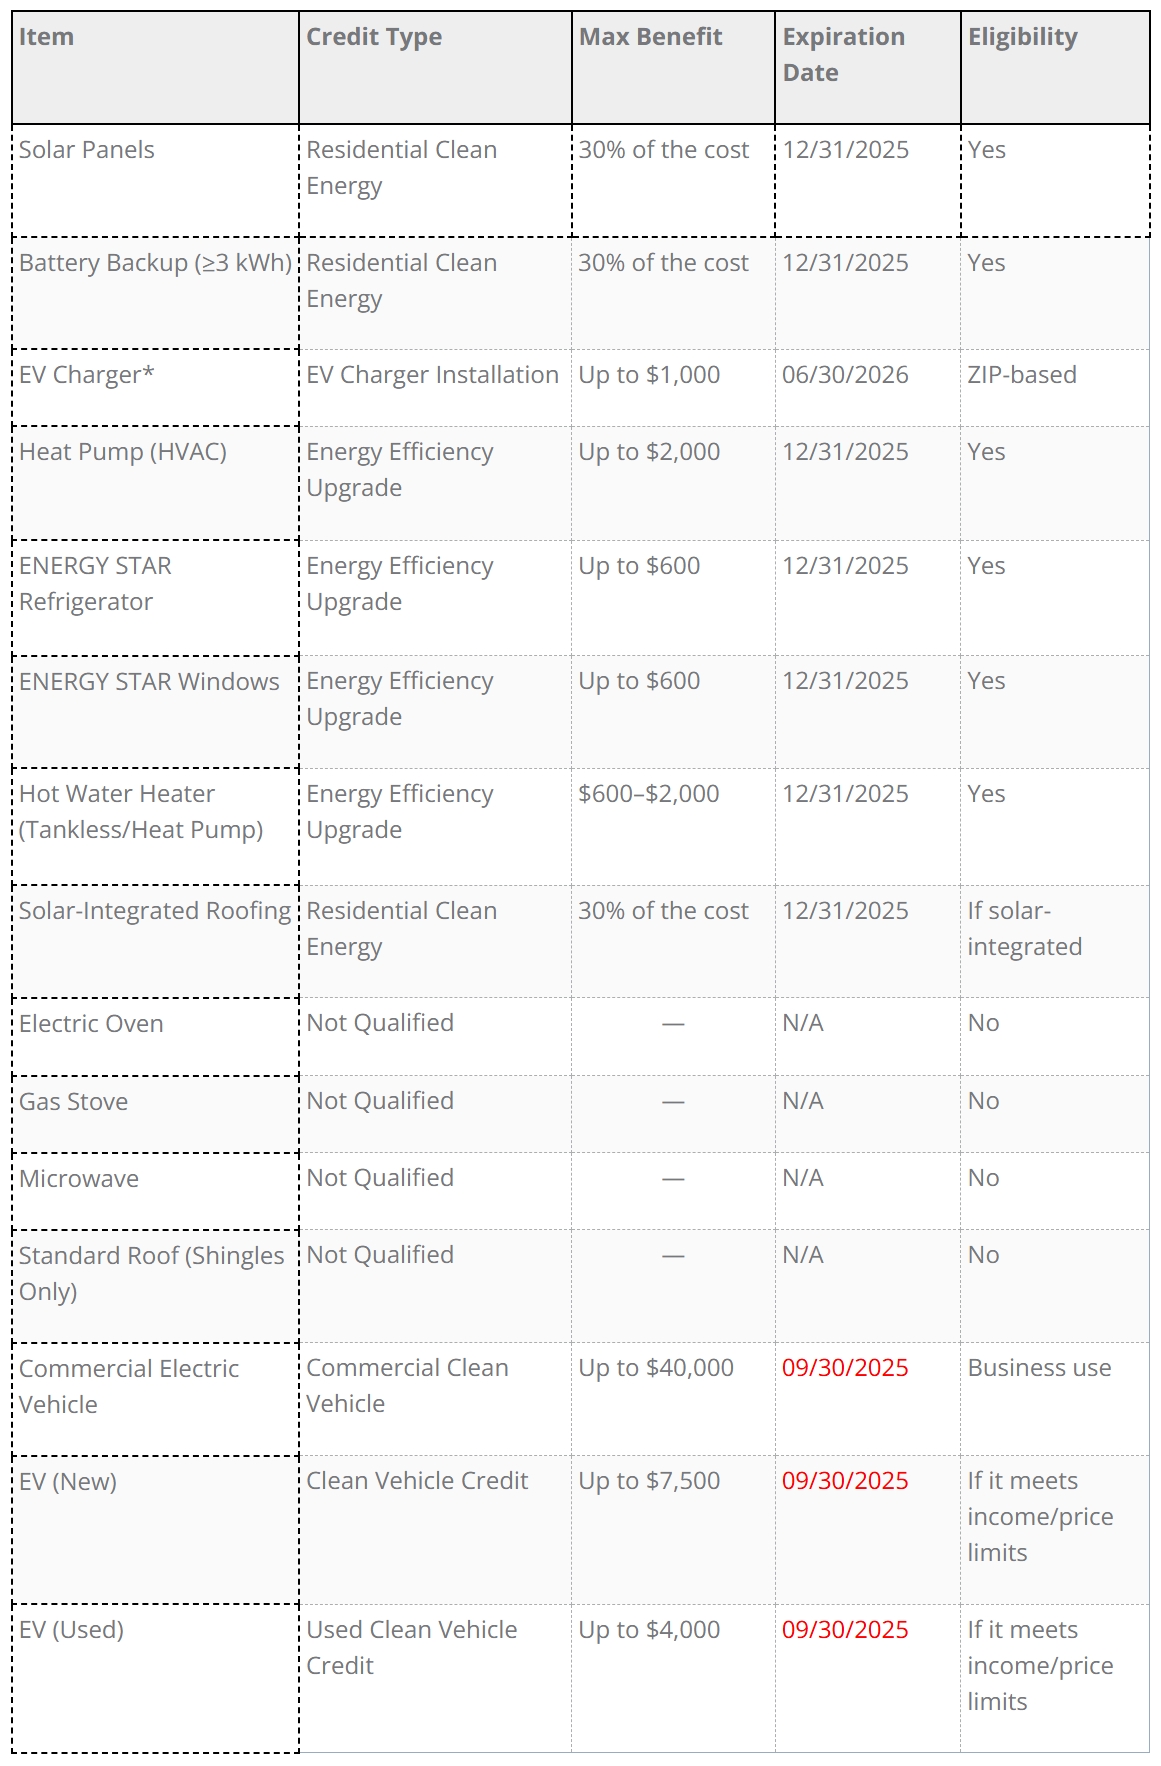
*EV Charger Credit requires property to be in a qualified low-income or rural area for eligibility.
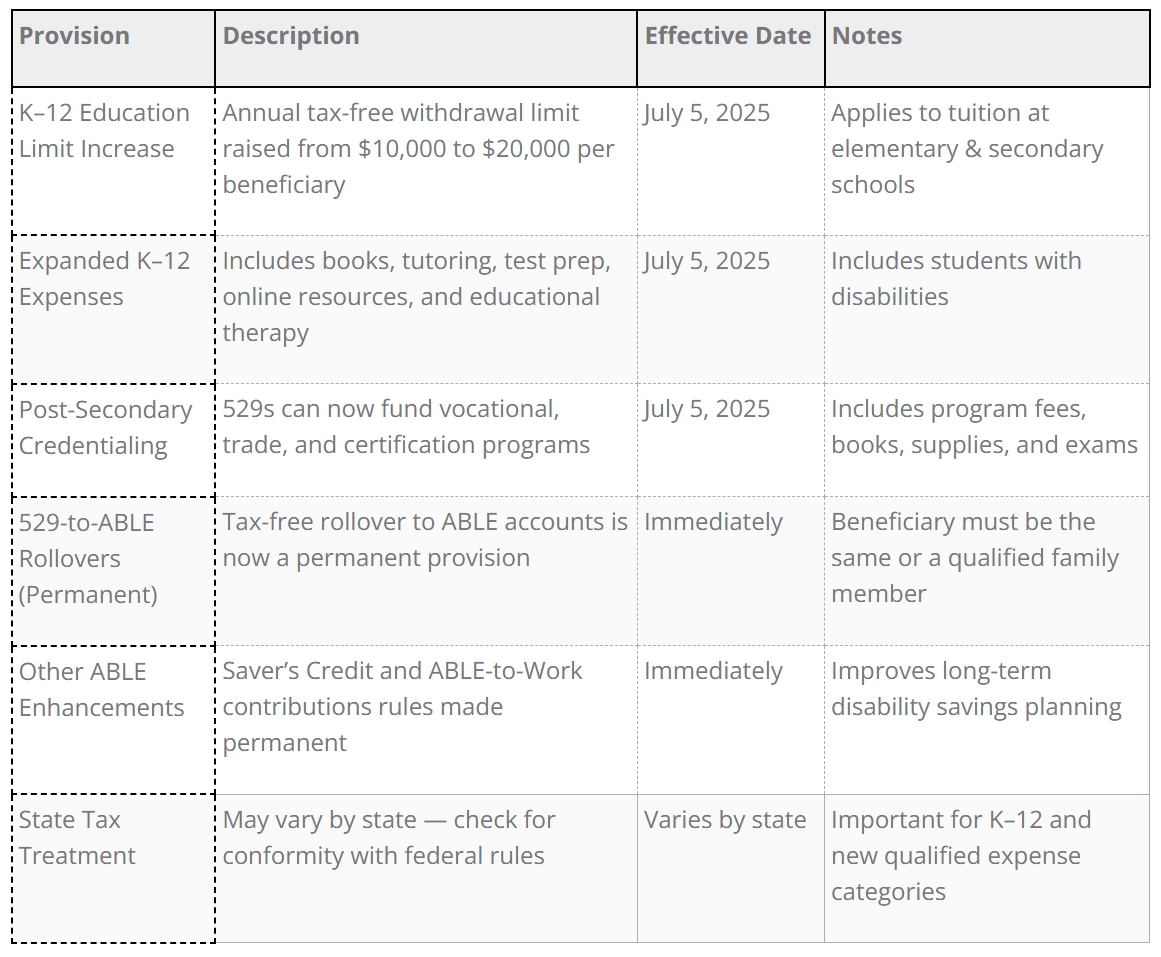
13. 529 Plan Expansion – Effective for 2025
K–12 tuition withdrawal limit doubled to $20,000 per year and expanded K–12 expenses to cover books, tutoring, test prep, online learning, and educational therapy.
Broadens scope beyond traditional college education, and 529 funds can now be used for vocational, trade, and credentialing programs. Tax-free rollovers from 529 plans to ABLE accounts are now permanently allowed.
ABLE account enhancements like Saver’s Credit and ABLE-to-Work contributions are also made permanent. No stated income cap on withdrawing funds from a 529 plan.
529 Plan Changes Summary - Most Effective 7/5/2025
14. Health Savings Accounts (HSAs)
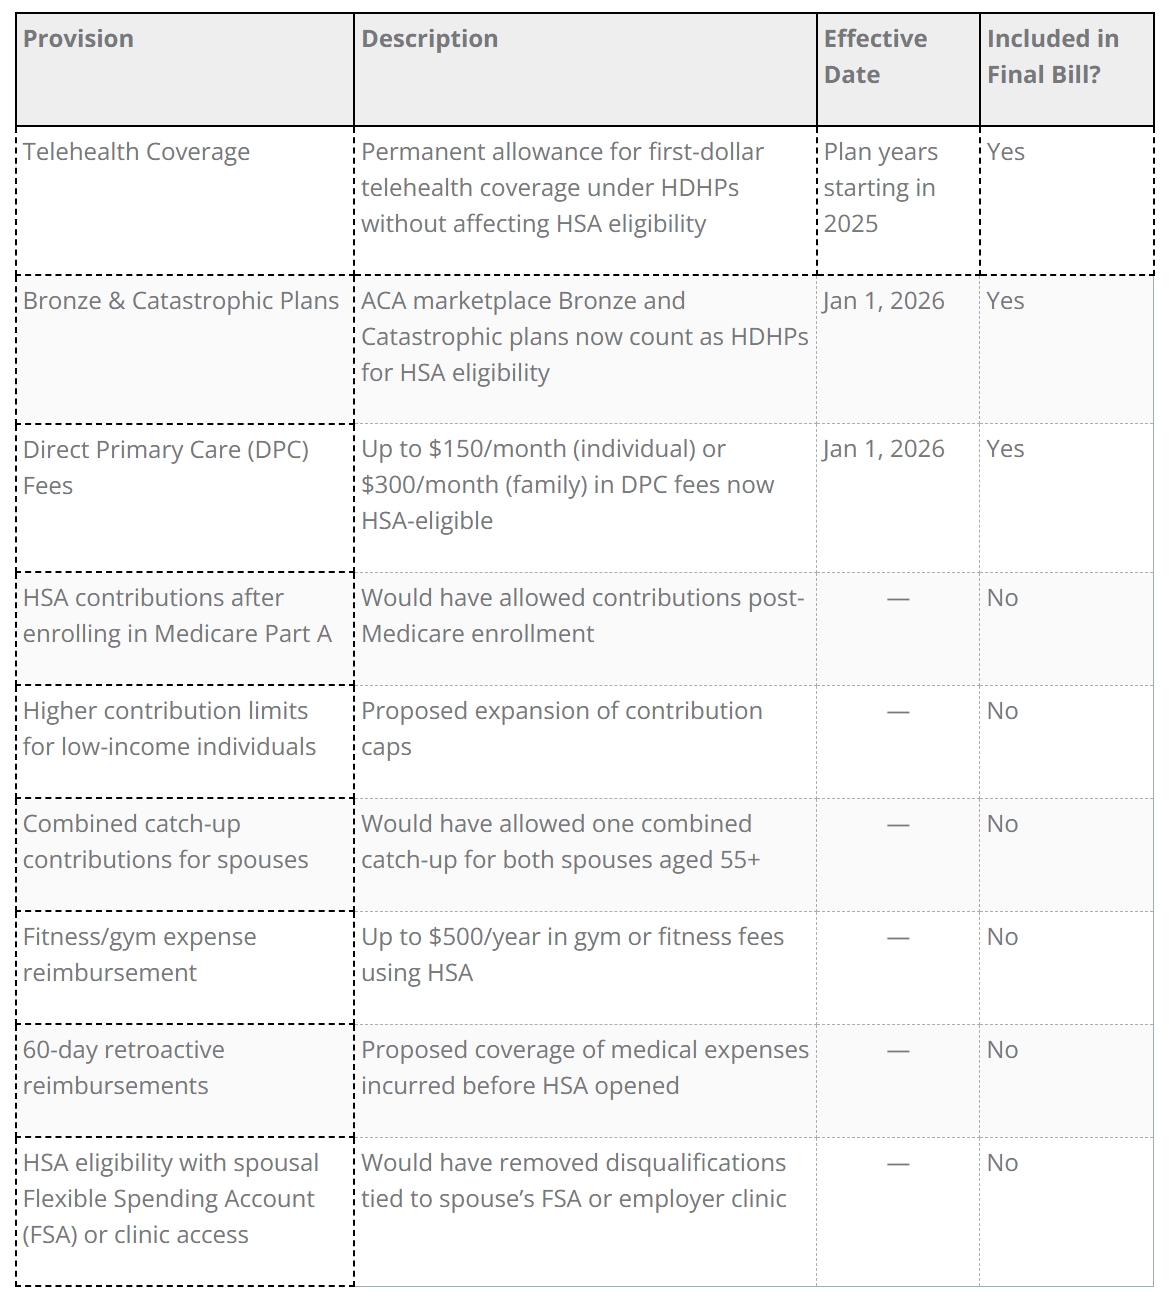
Permanent allowance for first-dollar telehealth coverage under high deductible health plans (HDHPs) without affecting HSA eligibility. Affordable Care Act (ACA) marketplace Bronze and Catastrophic plans now count as HDHPs for HSA eligibility. Up to $150/month (individual) or $300/month (family) in Direct Primary Care fees are now HSA-eligible.
OBBBA HSA Changes Summary
15. Mortgage Interest Deduction
Permanently extends the TCJA’s limitation of qualified residence interest deduction for the first $750,000 in home mortgage acquisition debt.
Business Taxation in the OBBBA
1. 100% Bonus Business Depreciation Made Permanent
Allows for the immediate expensing of 100% of qualifying property costs, permanently restoring the full write-off for businesses without income limits. Applied to property acquired after January 19, 2025.
2. Full R&D Expensing
Permanently allows full expensing of domestic specified research or experimental
expenditures (SREs) starting with the 2025 taxable year, reversing prior amortization rules— available to all businesses, no income limitation. Small business taxpayers (i.e., those with average annual gross receipts of $31 million or less) can apply the change retroactively to taxable years beginning after December 31, 2021. In addition, all taxpayers who capitalized domestic research or experimental expenses between December 31, 2021, and January 1, 2025, may elect to accelerate the deduction of any remaining unamortized amounts over one or two years.
3. Section 199A Qualified Business Income (QBI) Deduction
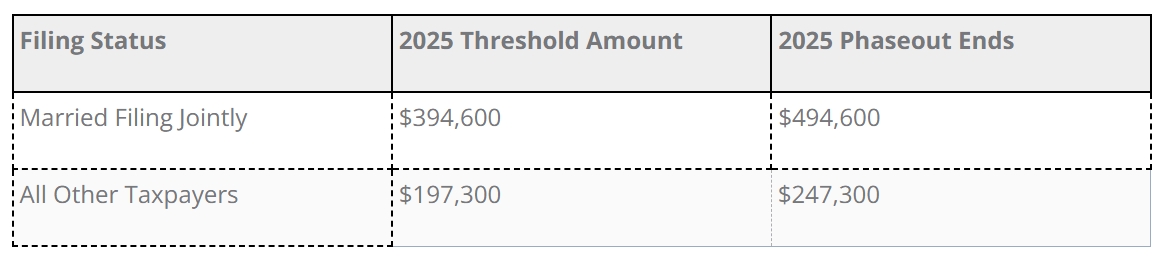
Makes the 20% QBI deduction permanent and adds a minimum deduction of $400 for taxpayers with at least $1,000 of QBI from an active trade or business, adjusted for inflation. Beginning with the 2026 taxable year, the phaseout ranges for purposes of computing the §199A deduction are increased from $50,000 ($100,000 MFJ) to $75,000 ($150,000 MFJ), which means that the size of the phaseout range is now wider.
Phaseout Ranges by Filing Status
4. Qualified Opportunity Zone (QOZ): New Series Approved – Effective for Tax Year 2027
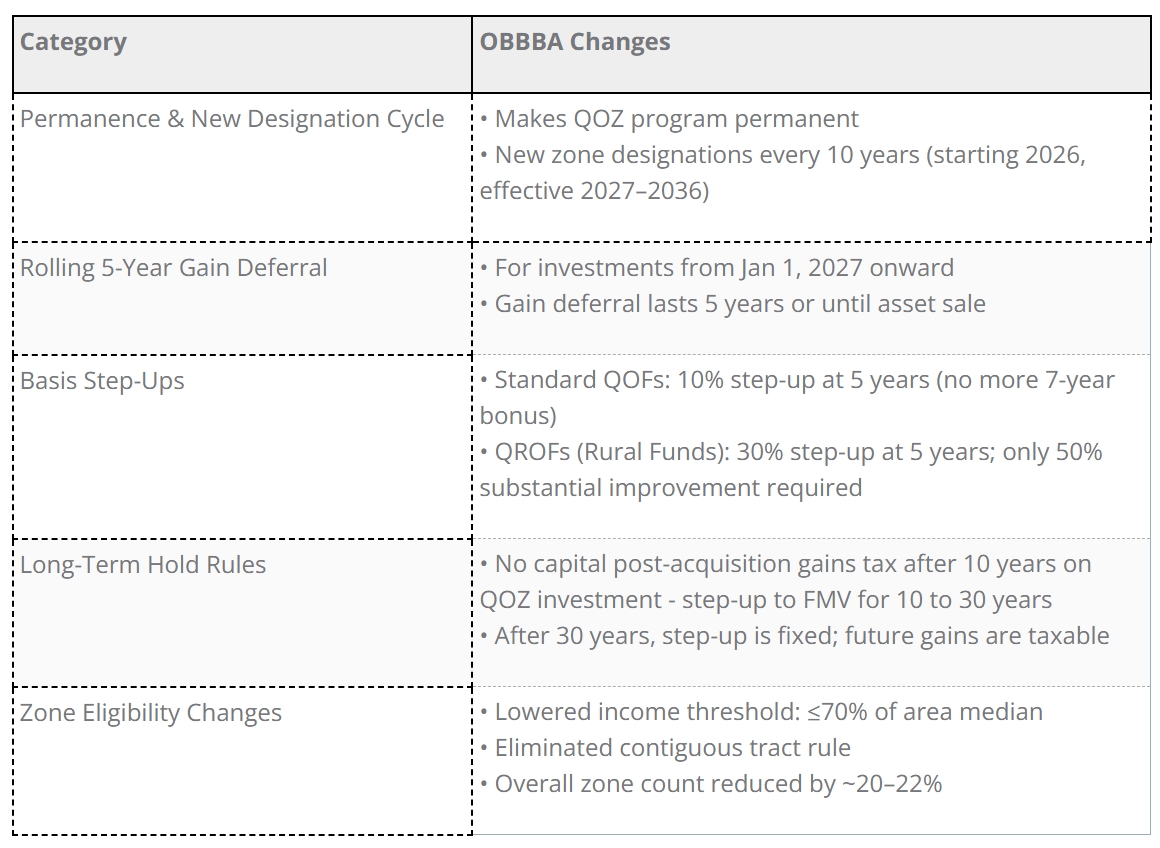
Permanently extends Opportunity Zones and introduces a new series of designated zones with a 5-year deferral of original gain. Enhanced tax incentives for rural QOZs.
Qualified Opportunity Zone Changes - 2027 Onward
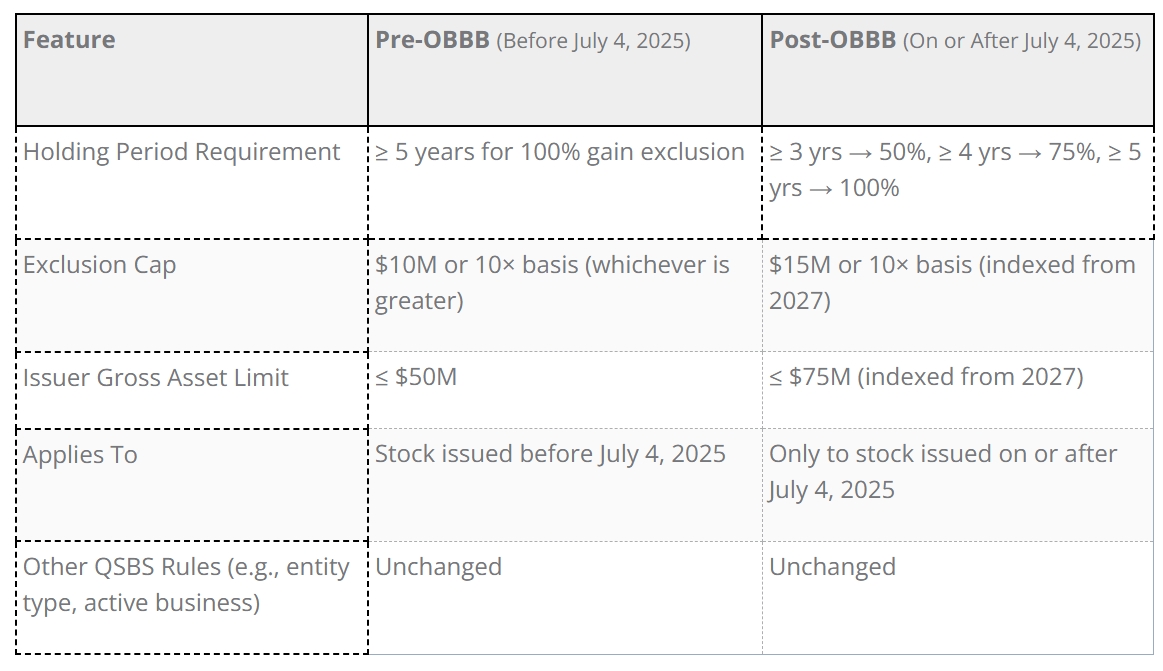
5. Qualified Small Business Stock (QSBS): Expanded Reliefs
Existing rules unchanged. For new investments made after July 4, 2025, there are new rules. Potential for partial relief after as little as three years.
Qualified Small Business Stock (QSBS) - Two Regimes
6. Section 179 Expensing
Raises the maximum Section 179 expensing limit to $2.5 million, reduced by the amount by which the cost of qualifying property exceeds $4 million, both of which will be adjusted annually for inflation.
7. Corporate Charitable Contribution Deduction
Establishes a floor of 1% of taxable income to deduct charitable contributions, up to a ceiling of 10% of taxable income. Effective after December 31, 2025.
If you have any questions about these updates, please contact BakerAvenue.
Baker Avenue Asset Management is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Any opinions expressed reflect BakerAvenue's views as of the date of the recording and are subject to change without notice. References to specific securities should not be construed as personalized investment advice and do not represent all securities purchased, sold, or recommended for client accounts. It should not be assumed that any investment discussed was or will be profitable. BakerAvenue, its employees, and/or its clients may hold positions in the securities discussed. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.


