July 2026: The BakerAvenue Prudence Indicator
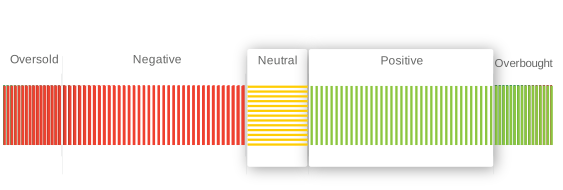
The BakerAvenue Prudence Indicator Says…
Summer 'Break'? More Dispersion, but Less Disruption
"I'm floating in a most peculiar way, and the stars look very different today."
- David Bowie
Markets are entering the historically volatile summer period near all-time highs but with a sharp positioning reset under way. Naturally, investors are concerned that the structure of the market may be breaking down. We see it differently. Since the market's prior high on June 2, the Magnificent Seven (MAGS) has lagged the equal-weighted S&P 500 (RSP) by roughly 10 percentage points, as previously crowded winners have cooled, and laggard performance has improved. We see this as a rotational, non-distributive market – a natural and historically healthy dynamic that tends to extend and strengthen bull markets rather than end them. A bumpier, but broader, performance backdrop should be expected.
While June consolidated returns (the S&P 500 was -1% in June), the strong 2Q (the S&P 500 was +14% in Q2) ranked as the strongest single quarter for the index since the pandemic recovery rebound in the second quarter of 2020. While there was some price trend pressure in leadership pockets (e.g., semiconductors), there was little evidence of sustained weakness. Since 6/2 (previous high), participation on down days has nearly doubled as dip buyers emerged. We see the backdrop as rotational and not distributive.
Importantly, fundamentals are tracking price. We’re seeing broader market participation as every sector is showing higher sales growth expectations today than at the start of the year. Operating margins have also expanded meaningfully and set a record. Growth resiliency is key to our market call (e.g., we have never seen a U.S. recession with corporate profit growth staying positive), and we continue to see more accelerating vs. decelerating fundamentals.
While the dynamic macro environment should keep volatility elevated over the next few months, growth resiliency has proven to be sustainable. We remain constructive. Investors should find plenty to do in portfolios while staying mindful of the lingering risks. More than a few investors have overlooked the tailwinds of sustainable growth, enduring industry themes, and repositioning that have propelled markets toward all-time highs over the past several months. While the uncertain macro environment raises the odds of a consolidation, we would expect investors to use potential dips as buying opportunities as the tailwinds for earnings growth remain underappreciated.
In times like these, it is important to have an investment process in place that removes emotion from the equation. At BakerAvenue, we maintain analytical independence from pre-written market narratives. We remove preconceived biases and defer to our analytical output. Ultimately, our views are only as optimistic or pessimistic as our technical, macro, and fundamental analyses indicate. Currently, our short-term metrics are in a neutral position while our longer-term view is positive.
For those who have been following our market updates (view previous market update videos and commentaries), you will be familiar with several of our key concerns and opportunities. We have continually stated our expectations of moderate growth. There are plenty of adjustments to consider, but our overarching views remain the same. Ultimately, economic and earnings growth will support a grind higher in equities. We believe it is a good time to be active and want to be thoughtful regarding portfolio construction and risk control.
The Technical Perspective
From a long-term perspective, price trends remain positive as we move through the heart of summer. Support lines remain upward sloping and leadership has been supportive, though pro-growth sectors are ceding some ground to the more defensive and previously neglected groups. The market is highly rotational, with factor performance and stock-level dispersion increasing meaningfully since the prior high in early June. We continue to see an opportunity for tactical repositioning as leadership shifts; we are intently focused here as we consider portfolio tilts.
We are looking for a sustained momentum thrust (e.g., expanding advance/decline lines, an expansion in new highs vs. lows, etc.) and steady volatility to help markets stay at, or eclipse, all-time highs. Internals remain steady, with a solid but improvable percentage of the S&P 500 trading above its 200-day moving average. A decent technical foundation raises the odds that corrective weakness, should it develop, is more likely to be contained. As active managers, we are encouraged by the higher performance dispersion within sectors and industries, as it supports more tactical oversight. We expect the lower correlation backdrop will continue this year, an environment we welcome.
The level of investor bullishness is more modest than what many suspect, given the strong price performance of late. We view that dynamic favorably. Our investor sentiment reads are still supportive, with bull-bear surveys and asset flows reflecting a neutral bias rather than euphoria. We have been noting that elevated money market balances should continue to act as a buffer to sizeable pullbacks. While not the overriding factor, investor positioning often influences the order of magnitude in market moves (higher or lower). While there is certainly a high bar for allocations given elevated risk-free rates, our view is that investors have room to increase equity exposure.
The Macro Perspective
The Iran conflict has added to the crowded macro headlines. Even prior to the conflict, the uncertainty surrounding shifting policies (e.g., trade, tax, monetary, etc.) had raised market volatility. Fortunately, a global fiscal spending cycle and decent economic growth are serving as powerful offsets. Current GDP growth estimates for ’26 are hovering around 2%; we see upside to those forecasts. We believe peak tariff uncertainty is behind us, which should create more visibility for corporate investment decision-making just as the benefits from the OBBB accrue and serve as a tailwind for growth.
Interest rates will continue to carry outsized significance. Why rates are moving (higher, or lower) is as important as the level. We believe ultra-low interest rates are a thing of the past and investors should embrace more normalized levels. We are encouraged by the fact that interest rates have moved higher as economic growth has proven resilient. With decent growth, the Fed doesn’t need to be aggressive with the size and number of rate cuts. We expect new Fed Chair Kevin Warsh to tweak the Fed’s approach to monetary policy while maintaining a growth bias.
The midterm election calendar adds another layer of seasonal consideration. Related headwinds have historically peaked in the late summer months, with volatility subsiding and return profiles improving on the other side; encouragingly, we expect this cycle to result in little material legislative change. Policy announcements more broadly continue to move at a fast pace, and most remain stimulative. We are aware of the uncertainty associated with the administration's approach but see counterbalances in many of its announcements, and we remain focused on judging the materiality of any declaration by assessing its impact on the key pillars of market performance (e.g., interest rates, earnings, investor sentiment, etc.).
The Fundamental Perspective
Fundamentally, we continue to focus on the trend in corporate profits and credit metrics. Headwinds, such as higher financing and input cost pressure, have been more than offset by acceptable demand trends. Estimates for revenues and profits have been revised higher over the past few quarters and were a stalwart defense against any bearish forecast. S&P 500 earnings growth for ’26 has jumped to over 22% from 10% expected at the end of last year and is up to 15% for '27. The upcoming quarter should be the second in a row of over 20% year-over-year earnings growth.
Profits are moving faster than prices, keeping valuations in check. The market is cheaper now than it was a year ago. Valuation dispersion within sectors and industries remains elevated with a historically sizable gap between the highest- and lowest-priced assets. We see opportunities in both groups (continued leadership in one, reversion to the mean in the other). Several of the secular growers are commanding high multiples, but also market-leading profitability. Value-oriented pockets offer opportunity, but investors will need to be selective. This is a key factor in our preference for staying active. We continue to advocate for themes like infrastructure and power demand, accelerating capital market activity, and AI-related efficiency gains.
The credit backdrop will be important to monitor as a check on fundamentals and a proxy for risk tolerance. The private credit concerns have yet to impact the public markets materially and credit spreads remain tight. Both investment-grade and high-yield spreads vs. Treasuries remain well below recessionary levels, and support our strong fundamental, and moderate economic growth views. Corporate cash flows remain healthy, and balance sheets are in good shape.
Concluding Thoughts
Markets have taken their foot off the gas heading into summer, but the composition beneath the surface looks very different than it did a few weeks ago. We characterize the backdrop as rotational, not distributive, and view it as a constructive dynamic that continues to widen the opportunity set for active managers. Factors within our technical, fundamental, and macro disciplines continue to skew positively on balance. Tactical consolidations are to be expected, particularly as AI spending scrutiny builds, earnings are reported, and midterm-related headwinds surface. The dynamic environment should keep volatility elevated, but growth resiliency has proven to be sustainable and is keeping us constructive.
Our investment philosophy is based on a dual mandate of growing and protecting client assets. We continue to focus on “how” one is positioned, not “if” they should have exposure at all. We are staying active, using volatility to harvest losses while opportunistically deploying capital where appropriate. At this point, our cash weightings remain residual in nature, and we are focusing on strategy positioning vs. our respective benchmarks to control risk. Of course, should the backdrop destabilize, we will take a more defensive stance.
Should you have any questions or comments, please contact BakerAvenue. We are happy to share our thoughts in greater detail, and we welcome the opportunity to speak with you.
About the author

Baker Avenue Asset Management is an investment adviser registered with the U.S. Securities and Exchange Commission. SEC registration does not constitute an endorsement of the firm by the Commission, nor does it indicate that the adviser has attained a particular level of skill or ability. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Any opinions expressed reflect BakerAvenue's views as of the date of the recording and are subject to change without notice. References to specific securities should not be construed as personalized investment advice and do not represent all securities purchased, sold, or recommended for client accounts. It should not be assumed that any investment discussed was or will be profitable. BakerAvenue, its employees, and/or its clients may hold positions in the securities discussed. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.