February 2024: The BakerAvenue Prudence Indicator
The BakerAvenue Prudence Indicator Says…
New High, Old Narrative
"The surest test of discipline is its absence."
- Clara Barton
Several broad equity indices recently made new all-time highs, with a few eclipsing big, round numbers (e.g., the S&P 500 climbed above 5,000). Theoretically, the actual number shouldn’t matter much. Underlying catalysts driving the move matter most (our approach leans heavily on technical, macro, and fundamental factors). And, mathematically speaking, each notable increment involves a smaller percentage increase, and is therefore easier to achieve. The move from 4,000 to 5,000 (25%) mattered less than the move from 3,000 to 4,000 (33%). Disclaimers aside, the succession of landmarks does fuel excitement and has been known to stimulate ‘animal spirits.’
We suspect resilient economic growth, surging mega-cap technology stocks, and optimism surrounding peaking interest rates have catalyzed the move. These tailwinds, unpopular less than a year ago, are now widely known and creeping further into consensus thinking. It is, therefore, imperative that the factors supporting those narratives are justified. And this is where we find comfort. Despite hitting new all-time highs, the market is less expensive and delivering greater earnings than at its previous peak in January 2022. Specifically, forward earnings estimates are +10% higher and valuations are -8% (or -1.8x multiple points) lower; more than 75% of S&P 500 companies trade at a discount to their January 2022 levels.
Returns following new highs tend to be good, particularly for those that took over a year to develop (e.g., the average forward return for the S&P 500 is over 14%). New highs are often accompanied by shifting market narratives, and this year is no different. New highs need narrative shifts, preferably positive ones. While it would be easy to assume little change given the markets’ encouraging consistency (e.g., the S&P 500 has been up 14 of the past 15 weeks), many of the defining characteristics of 2023 are showing subtle signs of changing, or, at the very least, becoming less influential. The overly concentrated nature of the market is showing signs of broadening. The Fed has taken the first step towards easing monetary policy (you must pause rate hikes before you lower them). And, importantly, earnings growth forecasts have been inching their way higher.
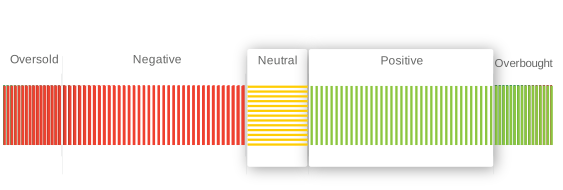
In times like these, it is important to have an investment process in place that removes emotion from the equation. At BakerAvenue, we maintain analytical independence from pre-written market narratives. We remove preconceived biases and defer to our analytical output. Ultimately, our views are only as optimistic or pessimistic as our technical, fundamental, and macro analyses indicate. Currently, our short-term metrics are in a balanced (neutral) position while our longer-term view is positive.
For those who have been following our market updates (view previous market update videos and commentaries), you will be familiar with several of our key concerns and opportunities. We have continually stated our expectations of slow but non-recessionary growth. There are subtle changes to consider, but our view remains the same. Ultimately, another year of economic and earnings growth should be enough to offset the higher rate backdrop and support a continued grind higher in equities. We believe it is a good time to be active and want to be thoughtful regarding portfolio construction and risk control.
The Technical Perspective
The technical backdrop remains volatile, but structurally intact. We believe the markets are in better technical shape relative to last month, with several indices holding steadily above key moving averages. Price momentum is strong, and internal metrics (e.g., market breadth, new highs vs. new lows, etc.) are moving off depressed levels. Small cap and equally weighted indices have lagged significantly over the past year and remain at multi-year relative lows but are showing signs of life. Despite the narrowness, leadership has remained within the pro-growth pockets of the market and defensives have lagged. We are intently focused here as we consider portfolio tilts.
We do expect the market to broaden out and leadership to continue to adjust as we move into the new year. Healthier markets tend to have strong participation rates, so we are on the lookout for improvement here. We are also encouraged by the higher performance dispersion within sectors and industries, as it supports more active oversight. We expect the lower correlations backdrop will continue into 2024, an environment we welcome.
Investor sentiment is now more balanced (e.g., bull-bear surveys have moved higher), but positioning remains light (e.g., investors have poured over $6 trillion into money market funds) and should act as a catalyst. While not the overriding factor, investor positioning often influences the order of magnitude in market moves (higher or lower). While there is certainly a high bar for allocations given elevated risk-free rates, our view is that investors have room to increase equity exposure as the lack of inflows already reflect considerable unease.
The Macro Perspective
The macro discussion must start with a view of the global economy. Incoming economic data continue to support our slow but not recessionary growth narrative. GDP growth has surprised on the upside here in the US for the last several quarters and estimates for the current quarter remain positive. Recent macro worries have centered on the mix of higher inflation combined with slowing growth and tighter financial conditions (e.g., restrictive monetary policy). We understand the concerns but continue to see peaking Fed policy as a sustained catalyst. We expect growth metrics to carry more influence (relative to inflation or rates) as we move deeper into the new year.
Interest rates will continue to carry significance, just less so. We don't think the lagged effects of prior policy tightening has been fully digested, thus our focus on growth. Yield curves have been inverted for well over a year as the front end of the curve has moved higher with Fed rate hikes. Curve inversion should be respected, as it has a very strong track record in signaling recessions over the past 40+ years. What they cannot predict accurately is the timing of the recession nor its depth and magnitude. One of the most pressing questions for investors is: Can the Fed get control over inflation without causing a deep recession? So far, so good.
Macro themes will remain important, no doubt, but we anticipate markets to sharpen their focus on specific security characteristics as the year progresses (e.g., company fundamentals, asset class relative strength, etc.). Security selection, identification of investable themes, and traditional bottom-up analysis will play an expanding role and help portfolios ride out the lingering macro-induced market gyrations. As the year progresses, geopolitical and political events will represent increasingly material considerations for investors. While particularly difficult to position for, we have several market- and non-market-based factors to lean on that help assess materiality and support positioning.
The Fundamental Perspective
Fundamentally, we continue to focus on the trend in corporate profits and credit metrics. Headwinds, such as higher financing and input cost pressure, have been more than offset by consumer spending resiliency and solid demand trends. Estimates for revenues and profits have been revised higher over the past few months and remain a stalwart defense against any recession forecast.
Valuations are in line with long-term averages. However, valuation dispersion within sectors and industries remains high with a historically sizable gap between the highest and lowest priced assets. We see opportunities in both groups (continued leadership in one, reversion to the mean in the other). Several of the secular growers are commanding high multiples, but also market-leading profitability. Value-oriented pockets offer opportunity, but investors will need to be selective.
The credit backdrop will be important to monitor as growth concerns persist. So far, the credit backdrop has supported the move in equities. One of the defining criteria between recessions and slowdowns has been the behavior of the credit markets. Both investment-grade and high-yield spreads vs. Treasuries have moved lower and remain at non-recessionary levels. Corporate cash flows remain healthy with dividend reinstatements (or increases) running well ahead of dividend cuts.
Concluding Thoughts
We welcome the new highs that have recently been established. The sharp move higher certainly raises consolidation odds, but history suggests forward returns are promising, particularly after the long spell between new highs. We have championed an active approach of investing with secular winners, while simultaneously allocating capital toward assets that will benefit most in a sustained recovery. We see no reason to alter that view. Our forecast for a maturing but sustained economic expansion strengthens our belief that investor focus should be on “how” one is positioned, not “if” they should have exposure at all.
Our investment philosophy is based on a dual mandate of growing and protecting client assets. We are staying active, using any volatility to harvest losses while opportunistically deploying capital where appropriate. Our cash weightings remain residual in nature and are focusing on strategy positioning vs. our respective benchmarks to control risk. Of course, should the backdrop destabilize, we will take a more defensive stance.
Should you have any questions or comments, please contact BakerAvenue. We are happy to share our thoughts in greater detail, and we welcome the opportunity to speak with you.
About the author

Baker Avenue Asset Management is an investment adviser registered with the U.S. Securities and Exchange Commission. SEC registration does not constitute an endorsement of the firm by the Commission, nor does it indicate that the adviser has attained a particular level of skill or ability. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Any opinions expressed reflect BakerAvenue's views as of the date of the recording and are subject to change without notice. References to specific securities should not be construed as personalized investment advice and do not represent all securities purchased, sold, or recommended for client accounts. It should not be assumed that any investment discussed was or will be profitable. BakerAvenue, its employees, and/or its clients may hold positions in the securities discussed. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.